
You said yes to that IRS payment plan when life looked different. Then the car died. Or your hours got cut. Now that monthly payment feels like a dare.
Good news first. An IRS payment plan change is allowed. You can ask to change IRS payment plan terms, and if money is truly tight, the IRS may approve a lower payment. Approval is never guaranteed, because the IRS makes the call.
Written by Arpita Shekhawat, Tax Hardship Center content team.
Quick Answer: Key Facts at a Glance
- An IRS payment plan change usually means a new monthly amount, a new due date, or a new bank account.
- You can change IRS payment plan terms online, by phone, or by mail.
- Requests to modify IRS installment agreement amounts need proof that your finances changed.
- Getting an IRS payment plan lower amount depends on your income, expenses, and filing status.
- Never just stop paying. Ask first.
What Is an IRS Payment Plan Change and Who Can Ask for One?
Think of your payment plan as a gym membership you signed up for in January. Great intentions. Now it costs more than your budget can hold.
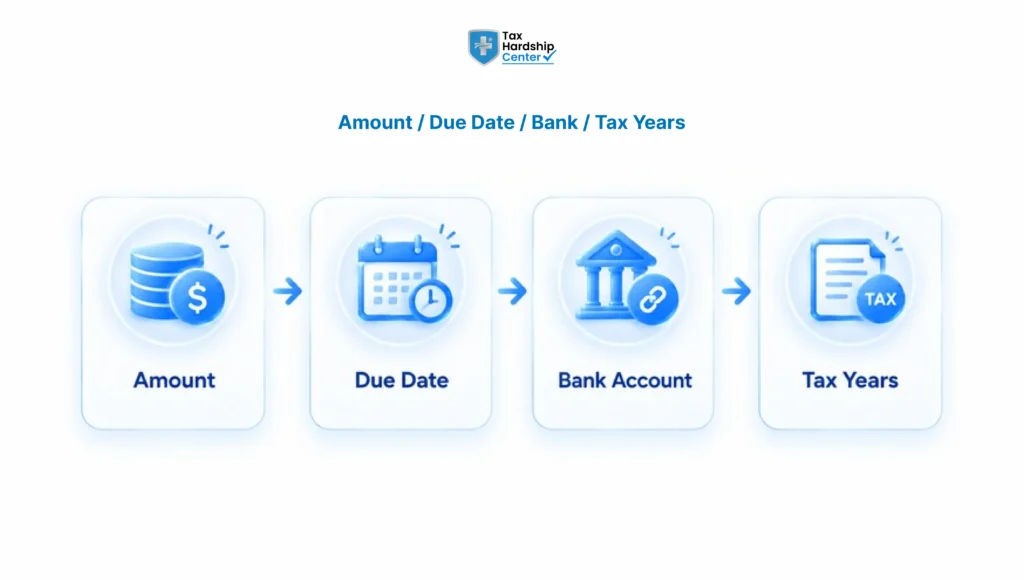
An IRS payment plan change is any request to alter an existing installment agreement. That includes:
- Lowering the monthly payment
- Moving the due date closer to payday
- Switching your bank account or payment method
- Adding a new tax year to the plan
Anyone with an active agreement can ask. Whether the IRS says yes depends on your numbers and your filing history. If you are still weighing which plan fits you, our guide to IRS payment plan options breaks down each type.
Can You Change IRS Payment Plan Terms After Approval?
Yes, and it is more common than you would think. If you want to change IRS payment plan details, the IRS Online Payment Agreement tool lets many people do it in minutes. Others have to call or write. The IRS page on payment plans and installment agreements lists current options and any fees.
The due date, bank account, and payment method are usually easy asks. The amount is the tricky one. A request to lower the payment gets more scrutiny, because the IRS wants to know why you cannot pay what you promised.
How Do You Get an IRS Payment Plan Lower Amount?
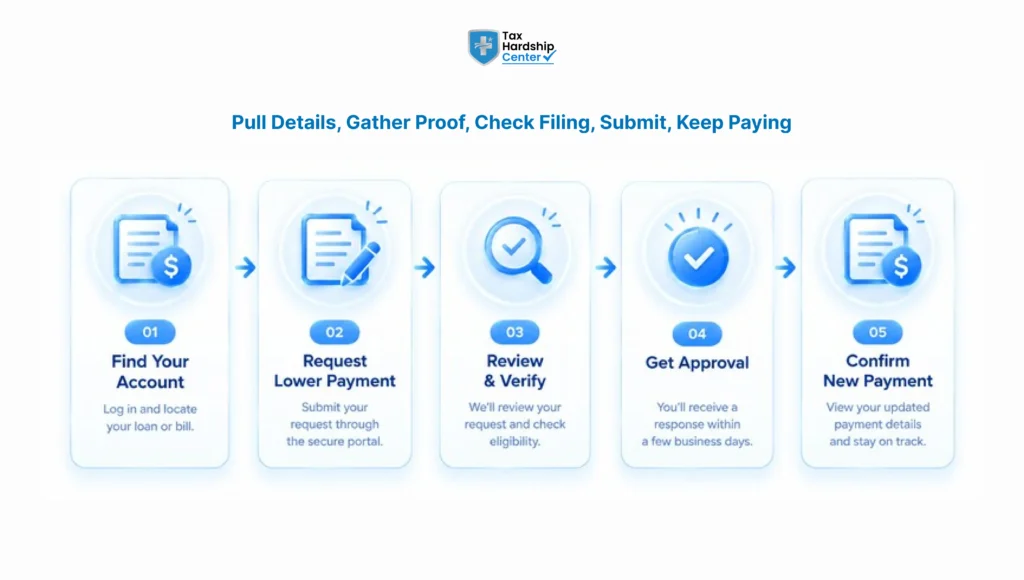
An IRS payment plan lower amount is not a favor. It is a financial argument. Here is how to make it:
- Pull your agreement details. Know your current payment, balance, and due date.
- Gather proof of what changed. Job loss, reduced hours, medical bills, or a new dependent.
- Check your filing status. All required returns must be filed, and new taxes must be paid on time.
- Submit the request. Go online, call the number on your notice, or use mail. Our Form 9465 payment plan guide explains the paperwork.
- Keep paying until the IRS confirms the new terms. Do not assume a request pauses your current plan.
Every IRS payment plan change request works better when your story matches your paperwork. Ask for a number you can actually sustain, not a hopeful one. A new IRS payment plan lower amount that you default on in two months helps no one.
What Will the IRS Ask for During an IRS Payment Plan Change?
Expect questions. The IRS may ask for a financial statement, often Form 433-F, which lists your income, expenses, and assets.
| What the IRS Reviews | Why It Matters |
| Monthly income | Shows what you can realistically pay |
| Necessary expenses | Housing, food, health care, transportation |
| Assets and savings | May be expected to cover part of the debt |
| Filing compliance | Unfiled returns can block approval |
| Current balance | Larger balances get closer review |
The IRS compares your expenses to its own allowable standards. That means your real rent or car payment may not be fully accepted. A smooth IRS payment plan change starts with honest math, not guesswork. Fees can apply to revise an agreement, so check before you file.
Should You Modify IRS Installment Agreement Terms or Pick Another Route?
Sometimes a lower payment is the right fix. Sometimes it only delays the problem. Here is the quick comparison:
| Option | Best For | The Catch |
| Modify IRS installment agreement | A temporary or moderate budget squeeze | Interest and penalties generally keep adding up |
| New payment plan | Adding new debt or rebuilding a defaulted plan | Fees and fresh review may apply |
| Currently Not Collectible (CNC) | Real financial hardship | Collection pauses, but the debt remains |
| Offer in Compromise | Inability to pay the full amount | Strict eligibility rules |
Not sure which one fits? Our breakdown of payment plan vs OIC vs CNC shows how each works. If you may never pay the full balance, check offer in compromise eligibility before settling for a smaller monthly payment.
A basic request to modify IRS installment agreement terms is usually the simplest path when your problem is temporary.
What Happens If You Skip the Change and Just Stop Paying?
Here is the plot twist nobody wants. Quietly skipping payments is not an IRS payment plan change. It is a default waiting to happen.

Missed payments or new unfiled returns can end the agreement. Then you may see notices like the CP504 final warning before levy, and enforced collection can follow. Interest and penalties keep growing the whole time.
Asking to change IRS payment plan terms before you miss a payment protects you. Asking after is harder. Same problem, fewer options.
Why Taxpayers Choose Tax Hardship Center for an IRS Payment Plan Change
If you need an IRS payment plan change handled correctly the first time, Tax Hardship Center is built for exactly that. We review your current agreement, income, and filing status, then tell you honestly whether a lower payment is realistic before you pay for anything.
In practice, we prepare the financial documentation, submit the request to modify IRS installment agreement terms, and handle IRS contact so you are not stuck on hold at 4 pm. Our IRS tax relief services cover individuals, and our small business IRS payment plan support helps owners juggling payroll and tax debt. We request an IRS payment plan lower amount only when your numbers support it, so you do not set yourself up for a second default.
Pricing should never be a mystery either. See how fees work in our tax relief service costs guide. The IRS controls the final decision, and we will say so upfront.
Click here to get a quote or call us at [phone number] to talk through your plan.
Conclusion
An IRS payment plan change is not a confession of failure. It is a correction, and the IRS expects them. Ask early, bring real numbers, and keep paying until you hear back. If you need to change IRS payment plan terms, the sooner the better.
P.S. What is the one bill that always wrecks your monthly budget?
FAQs
Can I change my IRS payment plan online?
Many people can. The IRS Online Payment Agreement tool allows some changes, like the due date or bank account. Others must call or write.
How do I ask the IRS for a lower monthly payment?
Request it online, by phone, or by mail, and be ready to show changed income or expenses. The IRS may ask for Form 433-F.
Does an IRS payment plan change cost money?
It can. The IRS may charge a fee to revise or reinstate an agreement. Check the current fee on IRS.gov before filing.
Can the IRS deny my request to modify IRS installment agreement terms?
Yes. Approval depends on your finances, filing compliance, and balance. If denied, you may have other options like a new plan or CNC.
Do I keep paying while the IRS reviews my request?
Yes. Keep making your current payments until the IRS confirms new terms in writing. Missing payments can put the agreement in default.
What if I cannot afford any payment?
You may qualify for Currently Not Collectible status, which pauses collection during hardship. The debt still exists, and interest may continue.
Key Takeaways
- Anyone with an active installment agreement can request a change.
- You can change due dates, bank accounts, and monthly amounts.
- A lower payment requires proof that your finances changed.
- The IRS may ask for Form 433-F to review income and expenses.
- Keep paying your current amount until the IRS confirms the new terms.
- Fees may apply when you revise or reinstate an agreement.
- Skipping payments can default your plan and trigger collection notices.
- A lower payment may not fix a debt you can never fully repay.
- The IRS decides the outcome, so honest numbers matter most.
Not Sure You Can Keep Up With Your Payment?
Get a free case review and find out what a realistic payment looks like.