
An IRS bank levy release is the IRS’s written order telling your bank to free your money. If you have a frozen IRS bank account, you usually have 21 days before the bank sends the funds to the IRS. A fast, documented IRS bank levy release request can stop that clock.
Your debit card declines at the pharmacy. The cashier tries it again. Nothing. Then the memory hits: those IRS letters in the kitchen drawer. Breathe. This is a rough scene, not the final one.
Quick Answer (TL;DR)
- The bank holds levied funds for 21 days before sending them to the IRS.
- An IRS bank levy release is possible if you pay, set up a payment plan, prove hardship, or show the levy was a mistake.
- Learning how to stop IRS levy on bank account balances starts with a call to the IRS and proof in hand.
- Not every case wins release, so get an honest assessment before paying anyone.
Why Is My Bank Account Frozen, and How Long Do I Have?
A frozen IRS bank account means the IRS sent a levy, a legal seizure of funds, to your bank. It rarely comes out of nowhere. It usually follows notices like the CP504 notice and the LT11 final notice, each one a warning that went unanswered.
Here is the plot twist most people miss. The bank does not wire your money on day one. As IRS Publication 594 explains, the bank holds the funds for 21 days. An IRS bank levy release issued inside that window keeps your money where it is. A levy also generally captures what is in the account that day, not every future deposit.
What Does an IRS Bank Levy Release Actually Do?
An IRS bank levy release is a formal notice, usually Form 668-D, that the IRS sends to your bank. It lifts the hold and tells the bank to return the funds to you. Your bank cannot grant one. Only the IRS can.
Think of the 21 days as the countdown in a thriller. Act before zero and the story changes. Wait past it, and the money is gone, and getting it back becomes a much harder fight.
How to Stop IRS Levy on Bank Account Funds Before the 21 Days End
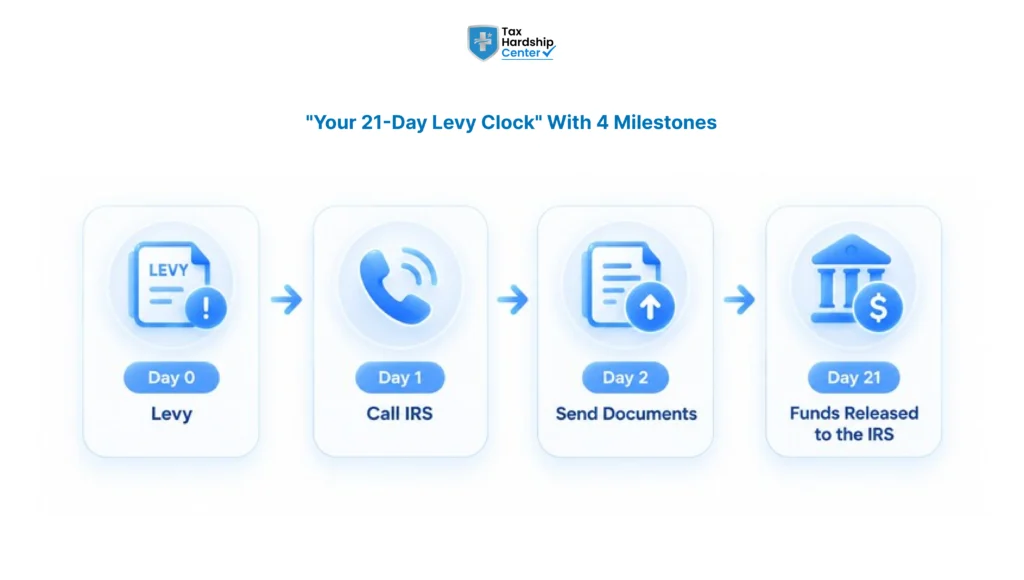
If you are searching for how to stop IRS levy on bank account funds today, speed and paperwork decide the outcome. Work in this order:
- Find your levy details. Note the levy date, your bank, and the IRS phone number on your notice.
- Call the IRS collections contact. Ask which release ground fits your case.
- Gather proof the same day. Pay stubs, rent, utilities, and recent bank statements support a Collection Information Statement (Form 433-A or 433-F).
- Offer a path forward. A payment plan or hardship claim gives the IRS a reason to release.
- Get it in writing. Confirm the release reached your bank, not just your inbox.
A tax resolution professional can often reach the right IRS unit faster and arrive with a complete file.
Which Situations Qualify for an IRS Bank Levy Release?
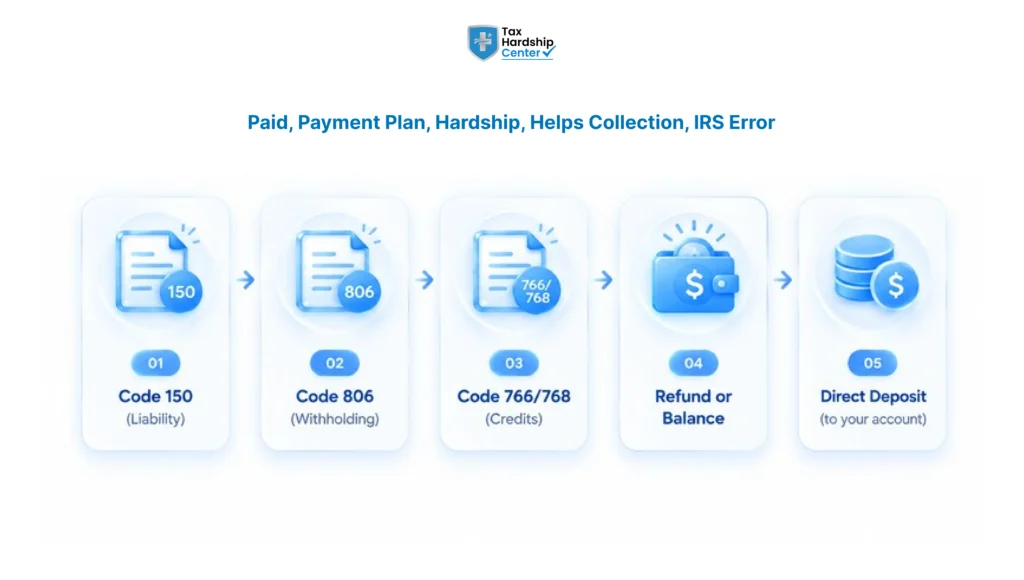
Under 26 U.S.C. 6343, the IRS must release a levy in specific situations. Here is the plain-English version:
| Release ground | What it means | Typical proof |
| Debt paid or unenforceable | Balance is satisfied or the collection window closed | Payment record, account transcript |
| Payment agreement | An installment agreement is in place | Signed agreement, first payment |
| Economic hardship | The levy blocks basic living expenses | Budget, bills, pay stubs |
| Release helps collection | Freeing funds lets you pay the IRS | Cash flow evidence |
| IRS error | Wrong taxpayer, amount, or missed procedure | Notices, IDs, transcripts |
Honest note: the IRS approves a release only when the facts fit a ground. A hopeful letter with no numbers rarely moves anyone.
How Do I Write an IRS Bank Levy Release Request That Works?
A strong IRS bank levy release request is short, dated, and loaded with proof. Include:
- Your name, last four digits of your SSN, and the levy date
- Your bank name and the amount frozen
- The release ground you are claiming
- One clear ask: release the levy now
- Attached documents that back the claim
Call first, then send your IRS bank levy release request in writing so a paper trail exists. If the freeze threatens food, rent, or medical costs, the Taxpayer Advocate Service accepts Form 911 requests for help.
What Mistakes Make a Frozen IRS Bank Account Worse?
- Waiting out the 21 days. The clock keeps running whether you call or not.
- Moving money around. Dodging one account invites levies on others.
- Closing the account. The bank still holds the levied funds.
- Calling with no documents. A release needs proof, not pleas.
- Skipping earlier deadlines. Many levies trace back to an ignored Letter 1058, which carries a 30-day window to request a hearing.
Is a Release Enough, or Do I Need a Permanent Fix?
An IRS bank levy release ends the freeze. It does not erase the debt. The IRS can levy again if the balance stays open, so pair the release with a real plan:

- Installment agreement: monthly payments you can sustain, explained in this guide to IRS payment arrangements.
- Currently Not Collectible status: a pause when paying would cut into basic needs. See how it compares with an Offer in Compromise and payment plans.
- Offer in Compromise: only for those who qualify, and not everyone does.
That is the real answer to how to stop IRS levy on bank account problems for good.
How Tax Hardship Center Delivers IRS Bank Levy Release Fast
When your money is stuck in a frozen IRS bank account, Tax Hardship Center starts with your levy paperwork, not a sales script. We read your notices, confirm your 21-day deadline, and tell you whether an IRS bank levy release is realistic before you pay for the wrong path.
Our team contacts the IRS for you, builds your Collection Information Statement, and files the IRS bank levy release request with documents attached. Once the levy is lifted, we move to a lasting fix: a payment plan, an Offer in Compromise for qualifying cases, or protection from the next step, including wage garnishment.
Cash is tight when funds are frozen, so we explain fees upfront. See how tax relief service costs work, then act while the clock is still running. The IRS decides outcomes, so we never promise a result, but we will tell you the truth about your odds.
Call us at [phone number] to talk to a tax specialist today.
Conclusion
A frozen IRS bank account feels like a cliffhanger, but the 21-day hold gives you room to act. Gather proof, call the IRS, and pair the release with a permanent plan. Moving fast gives you the best chance of keeping your money.
FAQs
Can I get my money back after the bank sends it to the IRS?
Usually not through a levy release, because a release stops a transfer but does not reverse one already made. In limited cases, such as a wrongful levy or a debt already paid, you may be able to seek the funds back.
How long does a levy release take?
Timing depends on the IRS unit and the quality of your paperwork. The 21-day hold is your outer deadline, so start the same day you notice the freeze.
How do I know my frozen IRS bank account is an IRS levy?
Ask your bank whether it received a levy and from whom. Your IRS notices can confirm it. Fraud holds and other creditors’ garnishments can look similar.
Can I file an IRS bank levy release request myself?
Yes. Call the IRS and send a written request with proof. Many people get help when hardship, unfiled returns, or a large balance are involved.
Can I stop an IRS levy without paying in full?
Often, yes. How to stop IRS levy on bank account balances without full payment usually means a payment plan, hardship claim, or proof of IRS error. The IRS decides case by case.
Can the IRS levy my account again?
Yes, if the balance stays unresolved. A release ends the freeze, not the debt, so you need a plan.
Key Takeaways
- The bank must hold levied funds for 21 days, so every day counts.
- Only the IRS can issue a release, not your bank.
- Release grounds include payment, an installment agreement, hardship, and IRS error.
- Call the IRS first, then send your written request with proof attached.
- Form 433-A or 433-F documents support a hardship claim.
- Knowing how to stop IRS levy on bank account funds means acting before day 21.
- Moving money or closing accounts usually makes the situation worse.
- A release ends the freeze but does not erase the tax debt.
- Payment plans, CNC status, and Offers in Compromise offer lasting fixes for those who qualify.
- Honest qualification before you pay protects you from the wrong path.
Click here to get a quote and get an honest read on your levy before the 21 days run out.